Basic (LAMal/KVG) & supplementary insurance

Health insurance, finally made clear.

Basic insurance covers the same care with every insurer. The price doesn't. Extras vary even more. We compare both and help you choose what fits your life. Free and independent.

What are you looking for?About 3 minutes
  • No health questions
  • No obligation
  • A person replies, not a bot
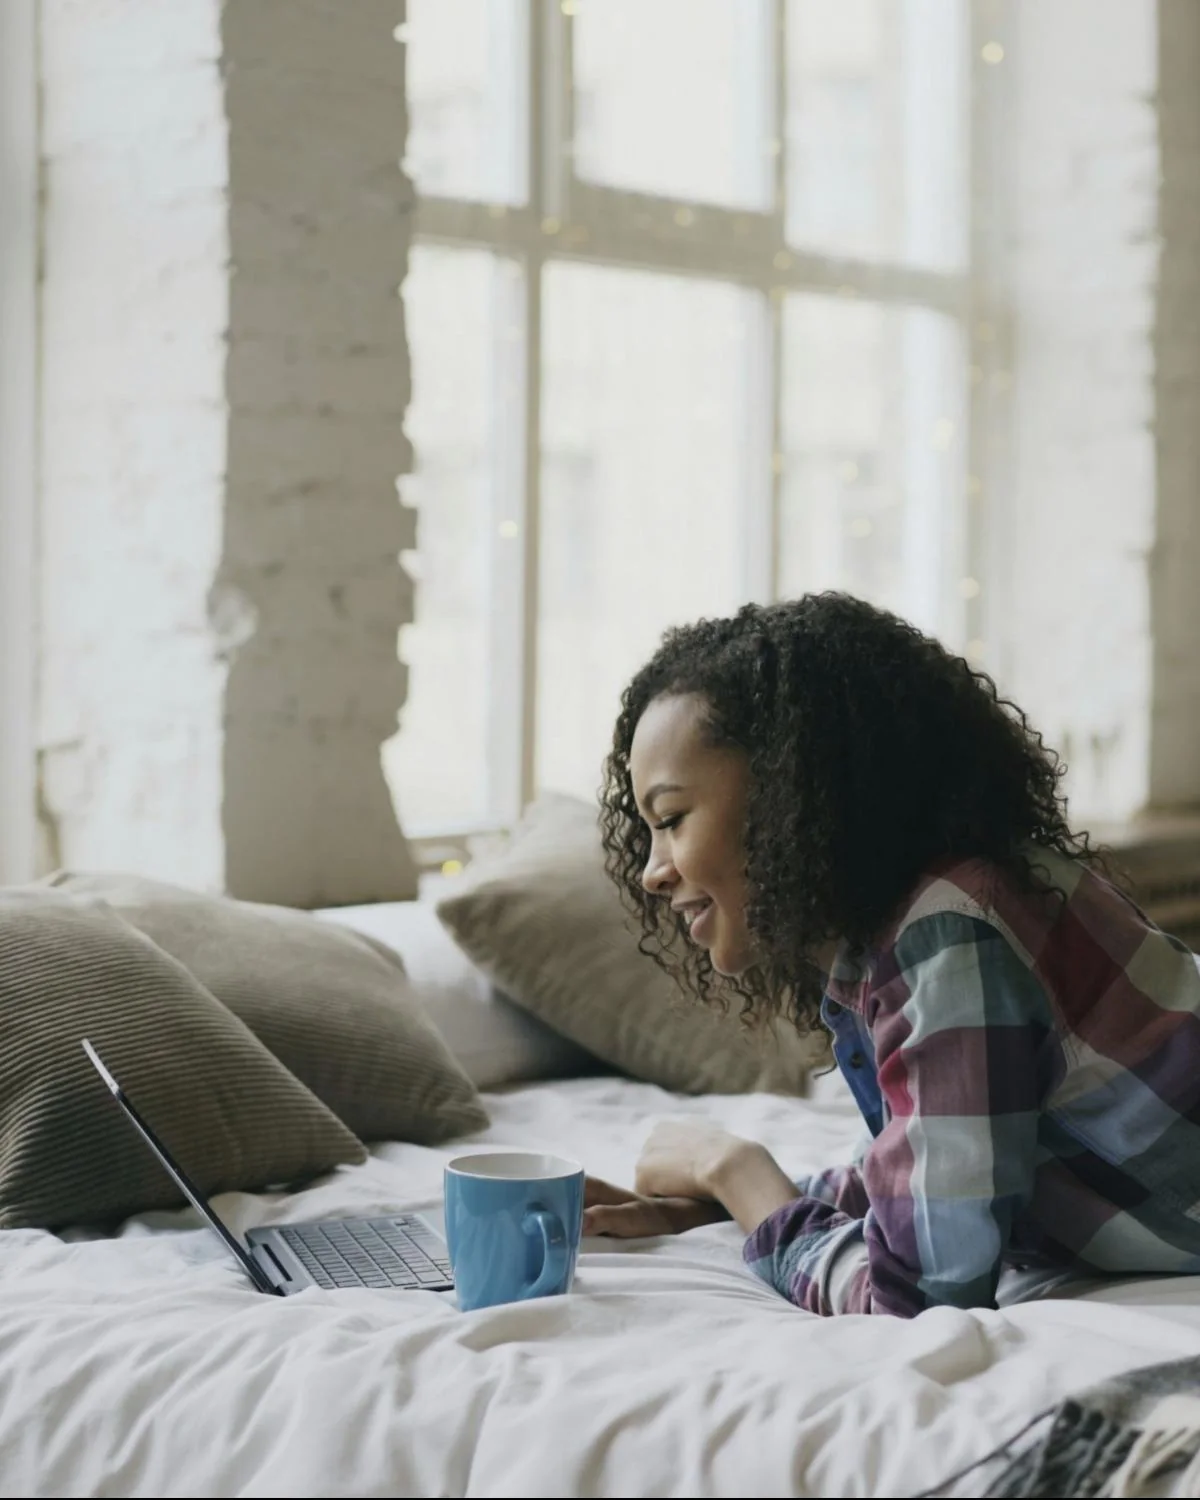
A young woman lying on her bed, smiling at her laptop with a cup of coffee
Switching basic insurance?Notice must reach your insurer by 30 November
We compare insurers including HelsanaCSSGroupe MutuelAssura
4.316 Google reviews ↗
How Swiss health insurance works

Two layers. Only one is mandatory.

Everyone living in Switzerland needs basic insurance. Supplementary insurance is optional: you add only the extras you want.

Mandatory

Basic insurance

LAMal / KVG
  • Same benefits everywhere. The law defines what is covered, so the care is identical with every insurer.
  • Insurers must accept you. Your health plays no role in basic insurance.
  • You choose the price. Insurer, doctor model and deductible decide your premium.
Optional

Supplementary insurance

LCA / VVG
  • Extras basic insurance doesn’t pay. For example dental care or a semi-private hospital room.
  • Insurers can say no. They may ask health questions before accepting you.
  • Mix and match. It can be with a different insurer than your basic cover.
Basic insurance

Four choices decide what you pay.

The cover is fixed by law. Your premium is not. These are the levers we look at with you.

Lever 1 · Doctor model

Choose how you enter the system.

Alternative models usually cost less than the standard model. In return you agree to start with a family doctor, a health centre or a medical hotline. Emergencies are always covered directly.

StandardSee any doctor or specialist directly.
Family doctorYour GP is your first point of contact.
HMOStart at a health centre.
TelemedicineCall a medical hotline first.
Supplementary insurance

Extras worth having. And the ones you can skip.

Nobody needs every extra. We look at what you actually use and leave out the rest.

Dental care

Basic insurance pays for almost no routine dental care.

Worth a look if you want help with check-ups or treatment.

Glasses & lenses

For adults, basic insurance generally doesn’t pay for them.

Worth a look if you wear glasses or lenses.

Hospital comfort

A semi-private or private room and more choice of doctor in hospital.

Worth a look if privacy in hospital matters to you.

Travel & abroad

Emergency costs abroad that go beyond what basic insurance pays.

Worth a look if you travel outside Europe.

Complementary medicine

Therapies that basic insurance doesn’t cover.

Worth a look if you use them regularly.

Prevention

Some products contribute to check-ups or fitness.

A nice extra, rarely a reason on its own.
Illustration: a health questionnaire on a clipboard, a pen and a shield
Good to know

Supplementary insurers can ask about your health.

They may decline an application or exclude conditions. That’s why we never ask you to cancel existing supplementary cover until the new one is confirmed.

This first check asks no health questions at all.

Timing

The dates that matter.

No rush. These dates simply decide when a change can take effect.

  1. Late SeptemberNew premiums are announcedYour insurer sends next year’s premium by the end of October.
  2. October – NovemberCompare and decideThe best moment for a review.
  3. 30 NovemberNotice deadlineYour cancellation of basic insurance must have reached your insurer.
  4. 1 JanuaryNew basic insurance startsNo gap in cover.
Supplementary contracts have their own notice periods, often longer. Check yours before cancelling anything.
Mid-year switch: with the standard model and the lowest deductible, notice by 31 March lets you switch at the end of June.
New in Switzerland? You have three months from arrival to take out basic insurance; cover applies from your arrival date.
With EVO Partners

Free advice, clear next steps.

  1. Tell us your situationA few questions, about 3 minutes. No health questions.
  2. Your adviser comparesBasic and supplementary options across insurers, explained in plain words.
  3. You decide, we handle itApplications and cancellations are done for you. Nothing changes without your signature.
Client reviews

In their words.

Published on evo-partners.ch. Individual results; your situation may differ.

JTJames T.Zurich
Marc-Antoine helped me save 620 CHF a year on my health insurance. Simple, fast, and truly with no commitment.
ELEmma L.Geneva
Finally a broker who explains things clearly. I switched insurer and model in a week.
MRMichael R.Basel
I didn’t know I was entitled to premium subsidies. Thanks to EVO Partners, I now receive 170 CHF/month.
Questions

Straight answers.

Something else on your mind? Ask us on WhatsApp.

No. Every insurer must accept you for basic insurance, whatever your age or health. That is not the case for supplementary insurance.

Not in this first check. If you later apply for supplementary insurance, the insurer will usually ask health questions. We prepare you for that and explain what it means before you apply.

The check and the advice are free for you. We explain how we are paid before you decide anything.

With the standard model, yes. With a family doctor or HMO model it depends on whether your doctor is on the insurer’s list. We check that for you.

Yes. Many people keep supplementary insurance with one insurer and choose a cheaper basic insurance elsewhere.

Basic insurance: your notice must reach the insurer by 30 November to switch on 1 January. Supplementary insurance follows the notice period in your contract.

No. You get a personal comparison and decide in your own time. Nothing is cancelled or signed without your explicit agreement.

Not sure where to start? Start with one question.

Three minutes. No health questions. A person reads every request.